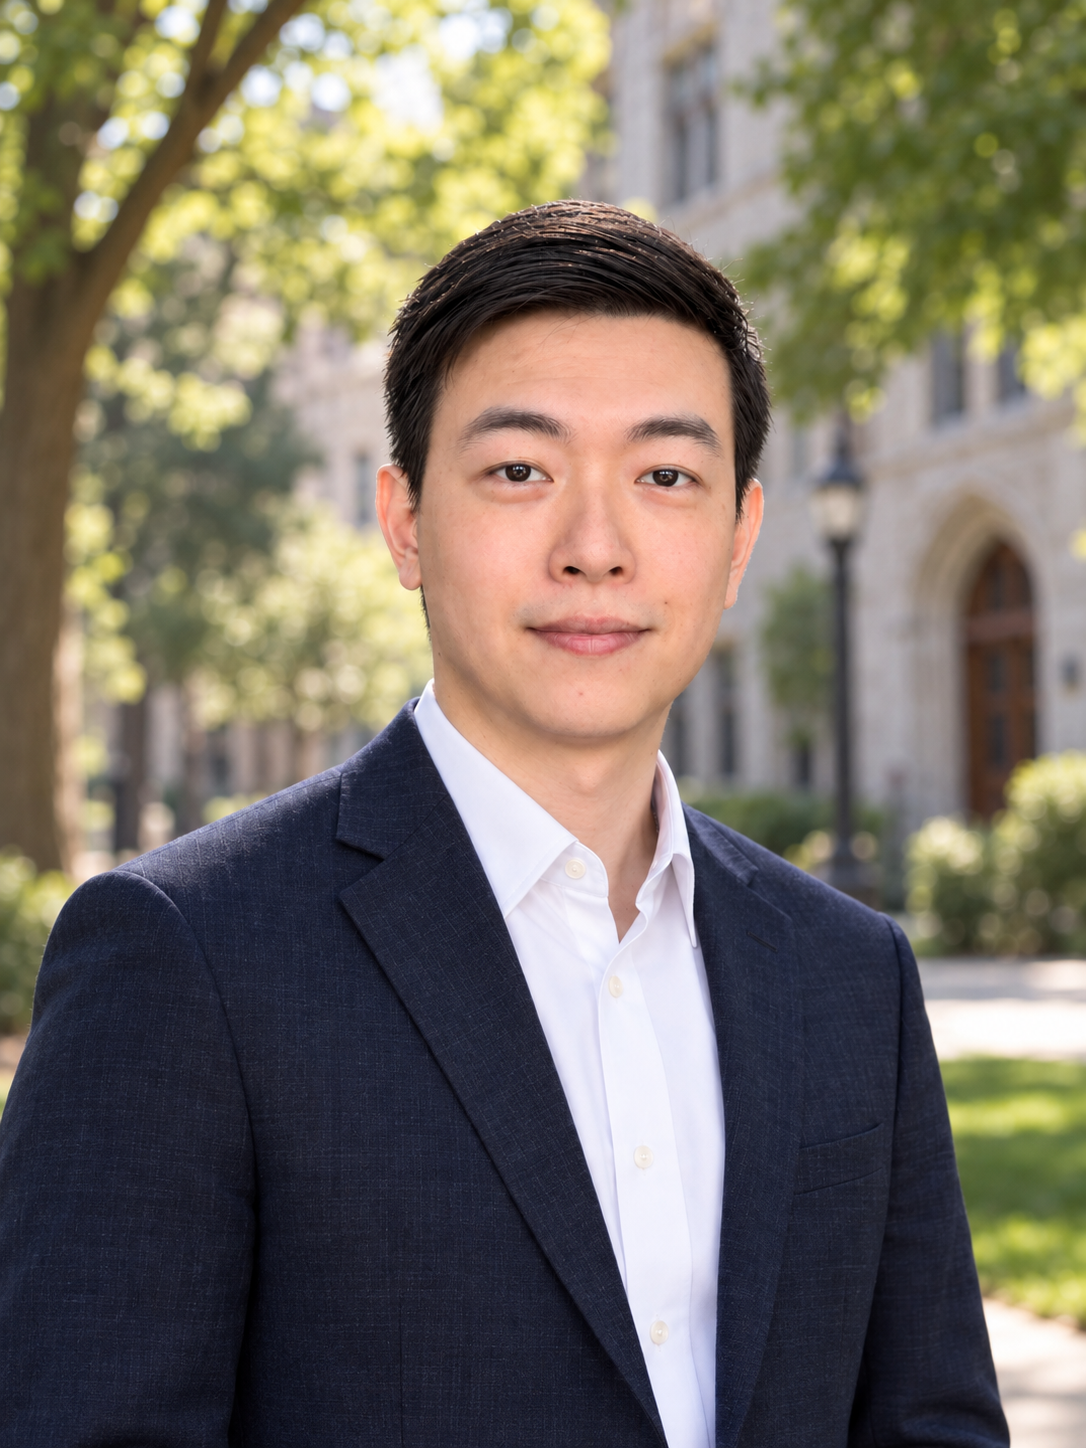
Yu-Yun Chang
Ph.D. Candidate in Economics
CUNY Graduate Center
Model Risk · Quantitative Validation · Macro-Financial Forecasting
My research focuses on exchange-rate dynamics, macro-financial forecasting, time-series econometrics, and machine learning. I am also building applied projects in model validation, data governance, and AI model risk.
Research
Is the Dollar Reconnect Forecastable? Information Timing and Exchange-Rate Predictability
Job Market Paper
This paper studies whether the post-2007 reconnect between the U.S. dollar and global financial variables translates into real-time exchange-rate predictability. Using 13 currencies through December 2025, I compare feasible forecast-origin information with a realized-regressor benchmark for the same exchange-rate target. The reconnect is strong in realized data, but forecast-origin performance remains weak, showing that much of the apparent forecasting gain comes from information realized during the forecast window.
Applied Projects
Current portfolio work includes:
- Independent validation of a GARCH volatility model
- Point-in-time financial data governance pipeline
- LLM / RAG system independent validation
- Model monitoring and inventory control framework
Contact
Email: ychang2@gc.cuny.edu